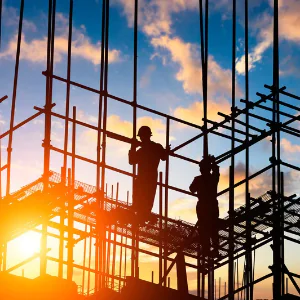
An owner’s representative pulls a superintendent aside on a Tuesday and tells him to add to the scope. The superintendent then puts workers on the job by Wednesday morning to keep the job moving. By Friday, the contractor has already paid for labor and materials, with no approved scope to bill against.
Weeks later, the owner still hasn’t signed the change order, and the contractor has to close the month reporting costs they cannot bill. Unapproved change orders become a reporting problem long before anyone treats them as a billing problem.
Strong construction change order management keeps a contractor from carrying those underbilling costs unchecked. Prager Metis construction experts work with contractors to evaluate WIP schedules, identify underbilling trends, and strengthen the internal controls that support accurate job costing, financial reporting, and decision-making.
Why Unapproved Change Orders Create Financial Risk
When a superintendent authorizes added scope in the field, the contractor adds workers right away, while invoices for extra material begin arriving shortly after. None of that cost recognition waits for paperwork, so the job absorbs the cost before anyone submits a change order for approval. A contractor cannot put revenue against that scope until the owner is contractually bound to pay for it and the amount looks collectible. An unsigned change order gives neither.
A National Association of Surety Bond Producers analysis named unapproved change orders as a standard cause of contractor underbilling’s. As part of their work with contractors, our construction advisors review WIP schedules, pending change order logs, and job performance reporting to help identify items that may affect working capital, profitability, or bonding capacity, particularly in advance of surety and lender reviews.
Common Warning Signs of Poor Change Order Management
Most contractors do not discover a change order problem after a single missed approval. Instead, they find it after the same failure repeats for a quarter or more, usually when someone finally reconciles the WIP schedule against what the field built. Contractors can usually identify these signs before that happens:
- Verbal approvals with no written documentation
- Work that begins before the owner approves revised pricing
- Inconsistent communication between project management and accounting
- Delays in updating budgets and forecasts
- Limited visibility into pending change orders
How Unapproved Change Orders Affect Cash Flow, WIP Reporting, and Profitability
An unapproved change order inflates a contractor’s working capital, pulls forward collections they cannot invoice, and leaves them pricing new work against margin their jobs haven’t yet earned. All three come off the same WIP schedule, which reports costs already spent with no revenue posted against it.
A surety reads a contractor’s construction financial reporting closely, starting with the same WIP schedule the controller prepares. In the NASBP analysis, an underwriter reviewed one contractor’s financials and found:
- Working capital inflated by nearly $3 million
- One project at 97% completion with $296,000 in underbillings that grew to $419,000 six months later at 99% completion
- 10 other jobs showing similar patterns
The surety removed those amounts from the contractor’s working capital calculation. Because a surety sets bonding capacity off working capital, a contractor absorbing a reduction of that size may have to pursue a smaller program than their backlog requires. And lenders read the same statements, so a contractor carrying inflated net worth can accept borrowing terms their real position cannot support.
The same schedule feeds the contractor’s own forecasting. A cash flow projection created off unapproved scope counts collections the contractor has no basis to invoice. Construction cash flow is tight on approved work alone, because owners hold retainage back on every billing. Contractors working from a padded forecast may plan against cash they will not see.
Margin is the last thing to correct itself. A contractor working from a padded WIP schedule could believe that jobs have earned more than they have, and end up pricing the next round of work off figures no owner ever agreed to.
How Prager Metis Supports Construction Clients
Our construction experts connect field activity to financial reporting. They work with owners, CFOs, controllers, and project teams to identify unresolved scope, assess underbilling exposure, evaluate WIP and backlog reporting, and strengthen the controls that support reliable decisions about bidding, staffing, financing, bonding, and growth.
How Construction CPAs Help
Most contractors can identify a pending change order. The harder question is how those items affect financial reporting, cash flow, profitability, bonding capacity, and future business decisions. Prager Metis construction experts help contractors:
- Review WIP schedules for underbilling trends and reporting risks
- Evaluate pending and unresolved change orders against job costs, forecasts, and billing status
- Assess the potential impact of underbilling’s on working capital, lender reporting, and bonding capacity
- Improve job costing, backlog forecasting, and the consistency of month-end reporting
- Strengthen internal controls surrounding change order approval, documentation, escalation, and reconciliation
- Turn financial reporting into practical insight for bidding, staffing, financing, and growth decisions
By bringing construction accounting knowledge and an outside perspective to the review, our advisors help management determine whether the WIP schedule reflects project reality, not merely the latest information that reached accounting.
Best Practices for Construction Change Order Management
By assigning key aspects of change orders to a named person on a fixed schedule, contractors can catch problems early. These five best practices give a contractor visibility into scope changes before they reach the WIP schedule:
- Standardize approval procedures: The contractor defines what authorization means in writing, including who can grant it, what form it takes, and what a superintendent does when an owner’s representative gives a verbal go-ahead before the business day starts.
- Track pending change orders separately: A controller maintains a log of every change order submitted and unapproved, with the submission date, the dollar value, and the job. They then review it against the WIP schedule before every month-end close.
- Update forecasts regularly: The accounting department rebuilds the cash flow projection on the same cycle as the WIP schedule and leaves unapproved scope out of expected collections.
- Align project managers and accounting teams: A project manager and a controller review open change orders together before month-end close, which gives accounting the field context and shows the project manager what an unapproved one does to the WIP schedule.
- Document every scope modification: Crews do not act on new scope until someone records the change, its pricing, and its authorization. A contractor that documents at the time of the change has a record to reconcile against when an owner questions the billing months later.
The Bottom Line: Protecting Profitability Before Additional Work Begins
Construction change order management pays off before a crew mobilizes, once a superintendent knows what authorizations are required and a controller knows what remains unapproved. Contractors with that level of discipline hand their sureties a WIP schedule that holds up while pricing new work against the margin their jobs have actually earned.
Every contractor takes on scope that moves faster than paperwork, but those that successfully protect project profitability decide in advance how far ahead of it they are willing to work. Strong change order controls provide better visibility into project performance, cash flow, and profitability.
Prager Metis construction experts help contractors improve WIP reporting, evaluate underbilling exposure, strengthen change order controls, and understand how operational decisions affect profitability, cash flow, and bonding capacity. Led by advisors such as Joseph Molis, CPA, CHFP, Partner, the team combines construction industry knowledge with financial and operational insight to help contractors make more informed decisions as they grow.
Speak with our Construction team about your WIP reporting, underbilling exposure, and change order controls.
Sources
- Abner, Mahki. “A Surety’s Perspective of Underbilling and Its Impact on Contractor Financials.” NASBP Pipeline, May/June 2025. https://www.nasbp.org/pipeline-newsletter/a-suretys-perspective-of-underbilling-and-its-impact-on-contractor-financials/